How to Increase Your Net Worth While Paying Off Debt
Most people think net worth is something you start building after the debt is gone. That's not how the math works. Net worth is what you own minus what you owe — which means every dollar of debt you knock out raises your net worth by exactly one dollar, immediately, with zero risk.
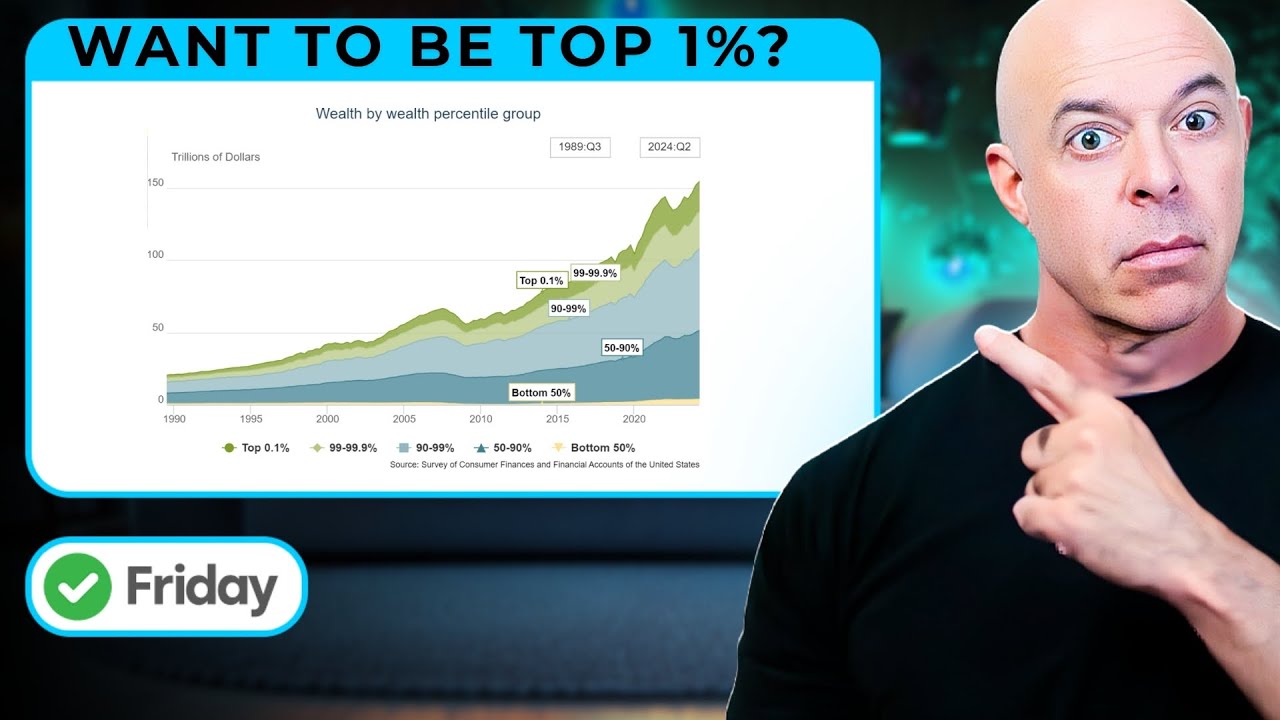
Brian walks through it on video.
So if you're staring at credit cards, a car loan and a mortgage and wondering how you'll ever get to the "building wealth" part, here's the good news: you're already doing it. You just need to do it in the right order.
What net worth actually is
Net worth = assets minus liabilities. Assets are things you own that hold or grow value: cash in the bank, a retirement account, index funds, gold or silver, a house, a car. Liabilities are what you owe: credit card balances, auto loans, student loans, the mortgage.
Here's an example. Say your picture looks like this:
| Item | Amount |
|---|---|
| Checking and savings | $3,000 |
| Car (market value) | $14,000 |
| Retirement account | $8,000 |
| Total assets | $25,000 |
| Credit cards | $10,000 |
| Auto loan | $17,000 |
| Total liabilities | $27,000 |
| Net worth | -$2,000 |
Negative net worth. That's not a character flaw, it's a starting line. And notice something: the fastest lever on that bottom number isn't buying anything. It's the $10,000 of credit card debt.
Why paying off high-interest debt is the highest-return move you have
A credit card at 22% costs you about $2,200 a year in interest on a $10,000 balance. Every dollar you throw at that balance stops costing you 22 cents a year. No investment gives you a guaranteed 22%. None.
Compare it to a savings account paying half a percent, or a short CD around 1.5%. With inflation running even at 2.4%, cash sitting in a regular savings account is losing buying power while your card is charging you twenty-plus percent. That gap is the whole argument.
Run your own number in the Credit Card Payoff Calculator. Put in your balance, your rate, and what you can actually pay each month — then add $100 and watch the interest total drop.
The worked example
$10,000 at 22% APR, paying $250 a month:
- Roughly 5 years and 11 months to clear it
- Roughly $7,600 in interest paid
Now pay $450 a month instead — an extra $200 found by cutting a couple of subscriptions and eating out less:
- Roughly 2 years and 4 months to clear it
- Roughly $2,500 in interest paid
That's about $5,100 you didn't hand to a bank, and your net worth is $10,000 higher three and a half years sooner. Then — and this is the part people miss — that $450 a month is now free. Over the next 2 years and 4 months, that same $450 going into savings and investments builds an asset column instead of shrinking a liability column.
Same money. Different phase. Both raise net worth.
The order that works
1. A starter emergency fund
Before you attack the debt hard, park something in cash. Without it, the next transmission failure goes right back on the card and you've undone months of work. How much depends on your situation — this breakdown walks through it.
2. Highest-rate debt first
Mathematically, the avalanche method — attacking the highest interest rate while paying minimums elsewhere — saves the most money. Some people need the psychological wins of the snowball. Both work; compare them here or run both in the Avalanche vs. Snowball tool.
3. Consider a 0% balance transfer if you qualify
Moving a 22% balance to a 0% intro card can accelerate everything — but the transfer fee matters. Check whether it clears in the Balance Transfer Break-Even calculator before you apply.
4. Attack the car loan next
Car loans are a double hit on net worth: you owe money on something that's losing value. If you owe more than the car is worth, you're underwater and it's dragging your net worth down every month. The Auto Loan Early Payoff Calculator shows what an extra $50 or $100 a month does.
5. Then start moving dollars into assets
Once the high-interest debt is gone and your emergency fund is real, the surplus goes to work. This is where the asset side of the ledger starts growing on its own.
Why the asset side matters so much
Look at what's happened to prices. Inflation ran around 8% to 10% in 2021, 2022 and 2023, and those higher prices never came back down. Groceries, cars, houses — all reset to a new level. If you held $10,000 in cash through that stretch, you didn't lose dollars, but you lost buying power. $1,000 in cash a year later might buy about $950 worth of stuff.
Assets moved the other direction. In the fall of 2024, gold was around $2,719 an ounce. Silver was around $32.21 — up roughly 50% on the year, meaning $1,000 would have become about $1,500. The Dow was up about 27% over the prior year. The S&P 500 was up about 33% since the start of that year. Bitcoin was around $67,000 and ethereum around $2,600, both volatile but both up.
That's the mechanical reason the household wealth charts look so lopsided. The people whose net worth exploded were holding assets. The people holding mostly dollars watched inflation eat the difference.
You don't need to become an expert
If owning gold or Bitcoin sounds complicated — vaults, wallets, keys — it doesn't have to be. Spot ETFs exist for gold, silver, Bitcoin and ethereum. Put $1,000 into a spot gold ETF and the fund is obligated to buy $1,000 of gold. You hold shares, you can sell them whenever, and it's all inside a normal brokerage account. Index funds do the same thing for stocks: one purchase gets you the Dow 30 or all 500 S&P names without picking a single stock.
Six straightforward options — gold, silver, Bitcoin, ethereum, a Dow index, an S&P index — is enough to be diversified. There's risk and volatility in all of them, and if you work with a financial advisor, that's a good conversation to have. This is education, not advice.
Track it, don't guess
The single habit that changes this from a plan to a result is measurement. Write down your assets and liabilities on the same page once a month. Watch the liability column shrink. Then watch the asset column start climbing. Use the Debt-Freedom Tracker so you can see the line moving instead of wondering.
The bottom line
You do not have to choose between getting out of debt and building net worth — paying off debt is building net worth, and it's the version with a guaranteed return. Clear the 20%-plus balances first, keep a real emergency fund in cash, then redirect that freed-up payment into assets so inflation stops quietly taxing your savings.
Start by running your actual numbers in the Debt Avalanche Calculator, then check where the rest of your plan should go with Investing While in Debt. One phase at a time, and the bottom line moves.