Why the Wealthy Hold Assets Instead of Dollars (And How to Start Doing It)
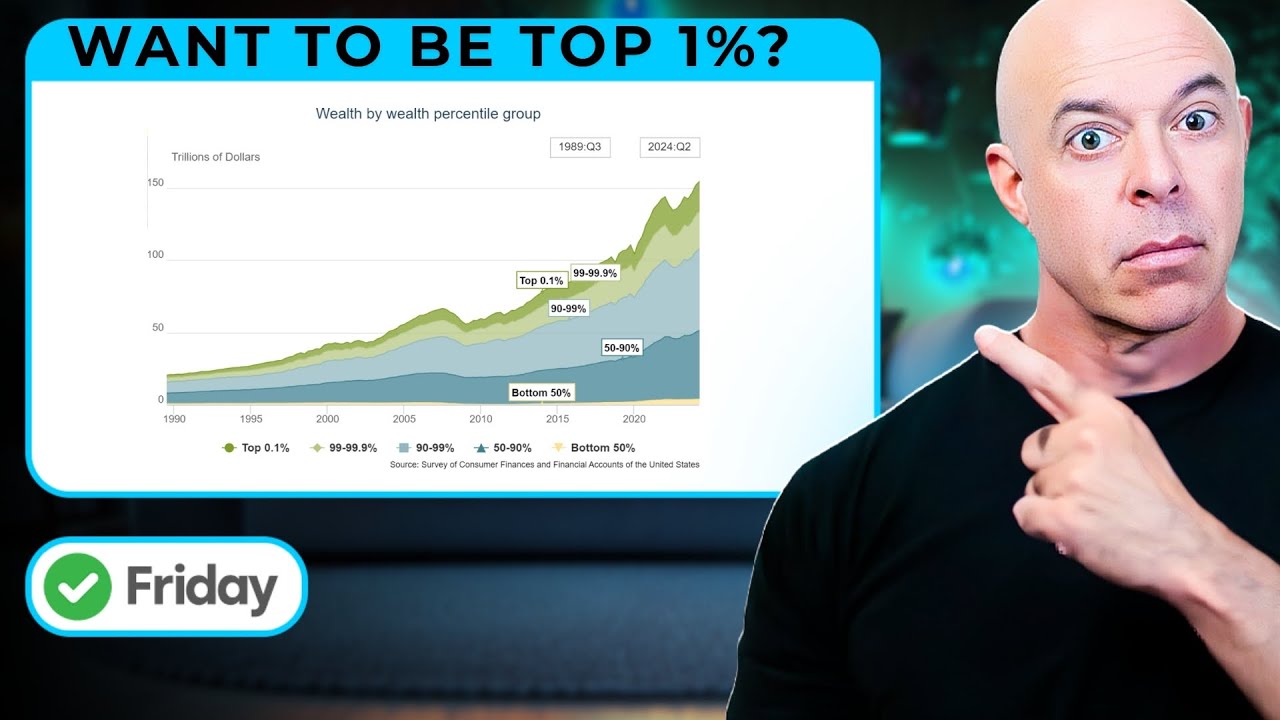
This is my weekly Friday show — the one I call "the dollar is dead." I started it back in February 2024 because I wanted to document, week after week, what actually happens to your money when you hold dollars versus when you hold assets.
No hype here. Just a wealth chart, the current inflation rate, savings and CD rates, gold, silver, Bitcoin, ethereum, the Dow and the S&P 500 — and a simple way anybody can own those things without becoming an expert. I'm not a financial advisor, this is informational only.
What you'll learn
- What the household wealth chart shows about the bottom 50% versus the top 0.1%
- Why inflated prices from 2021–2023 never went away
- How savings and CD rates compared to inflation on the day I recorded
- What a spot ETF is and why it's the easy way to own gold, silver, Bitcoin or ethereum
- Why I check the 2-year and 10-year Treasury every single Friday
The wealth chart that started the conversation
I pulled a chart of American household net worth from 1990 through Q2 of 2024. The bottom 50% of Americans — half the country — showed a tiny sliver of growth. The next 40% showed a big jump. The next 9% showed another big jump. Then just 0.9% of Americans, and finally the top 0.1%, showed staggering growth. Credit where it's due: this came from Ben Carlson's blog, A Wealth of Common Sense.
The numbers he lays out: collective U.S. household net worth was roughly $66 trillion at the end of 2007. The 2008 crash wiped out about $11 trillion, leaving about $55 trillion by 2009. Since then we've gained about $100 trillion, and since 2020 households have added about $50 trillion — netted out for debt. That's a staggering amount of wealth created in a short period.
Why did it land so unevenly? Because the wealthy hold assets, not dollars.
Inflation and what cash actually earns
Inflation the month I recorded was 2.4%, down from 2.5% and 2.9% in prior months, and 3.5% and 3.7% earlier. But look back at 2021, 2022 and 2023 — we hit 8%, 9%, close to 10%. Those inflated prices never went away. Groceries, cars, houses, stocks, gold, silver — all more expensive and staying that way.
Meanwhile, the FDIC national rates that month: savings about half a percent, a 3-month bank CD at 1.55%, a 3-month Treasury at 5.21%. Only one of those was really beating inflation, and there have been long stretches where none of them did. Money sitting in the bank just loses buying power.
What assets did instead
Gold was $2,719 an ounce. Silver was $32.21 — up roughly 50% on the year. Put it in plain terms: $1,000 in cash might buy about $950 worth of stuff a year later. That same $1,000 in silver would have been about $1,500. Bitcoin was around $67,000, ethereum around $2,600 — volatile, but up from the start of the year. The Dow was up 27% over the past year. The S&P 500 was up 33% since the beginning of the year.
The easy way in: spot ETFs and index funds
If you're thinking "I don't know how to buy gold or hold Bitcoin in a wallet," you don't have to. Go to your broker and buy a spot ETF. Put $1,000 into a spot gold ETF and they're obligated to go buy $1,000 worth of gold. You can buy and sell those shares any time — they're liquid. Same idea with index funds for the Dow 30 or the S&P 500: they buy the stocks so you don't have to. Plenty of books have been written about how hard the S&P 500 is to beat over time, even for professional money managers.
That gives you six options — gold, silver, Bitcoin, ethereum, a Dow 30 index, an S&P 500 index — and a reasonably diversified way to own assets instead of dollars. If you have a financial advisor, talk to them; risk and volatility are real.
The Treasury inversion check
I closed with the 2-year at 3.9% and the 10-year at 4.09%. Normally the 10-year pays more, and that week it did. For much of the prior year it was inverted — the 2-year paying more than the 10-year. I track this because on the long-term chart, every gray recession band is preceded by an inversion. We just came out of one. That's not a prediction, it's a reason to keep your emergency savings solid.
Key steps
- Kill the high-interest debt first — credit cards at 20%+ beat any asset return. Run it in the Credit Card Payoff Calculator.
- Build an emergency fund and keep it in cash. That money isn't for gold or crypto.
- Check what your cash is actually earning against the current inflation rate.
- Once the high-rate debt is gone, move surplus dollars into assets — spot ETFs or index funds are the simple path.
- Track it weekly instead of guessing. That's why I do this show every Friday.
FAQ
Should I buy gold or Bitcoin while I still have credit card debt?
I'd pay the high-interest debt first. A credit card charging 20-plus percent is a guaranteed cost every month, while asset returns are never guaranteed. See the math in Pay Off Debt or Invest First? and use the Avalanche Debt Eliminator.
What is a spot ETF?
It's a fund that must hold the underlying asset. Put $1,000 into a spot gold ETF and the fund buys $1,000 of gold, so you effectively hold gold through shares you can buy and sell at your broker. Same structure exists for silver, Bitcoin and ethereum.
Why does an inverted yield curve matter to someone in debt?
Historically, recessions on the chart follow inversions. If layoffs are a possibility, your emergency fund matters more than squeezing out extra payoff speed. How to Prepare for a Layoff When You Have Debt walks through it.
The step-by-step written version, with a worked example.