Velocity Banking Myths: Two Things People Get Wrong About the Math
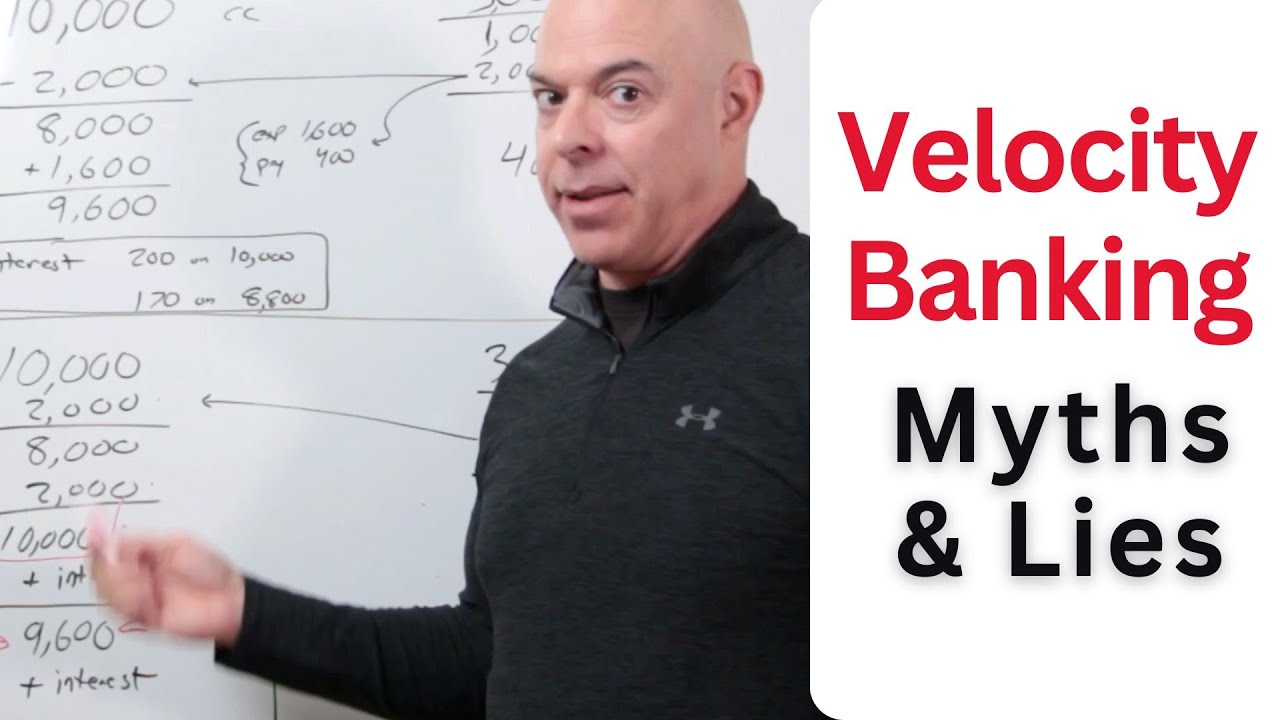
I've watched a lot of velocity banking videos, and I've made some of my own showing how velocity banking with a credit card works. Does it work? Yes. Is it as powerful as some people online make it sound? No. In this video I point out two things about the velocity banking method that I keep seeing and that are flat-out wrong, because they make it look way faster than it actually is.
What you'll learn
- How velocity banking on a credit card actually works, step by step
- Why leaving interest out of the calculation gives you a false payoff date
- Why "go get another job" isn't part of the method — it's a different method
- The basic math error behind the claim that a big payment "frees up" your minimum payment
- The one situation where the numbers people show you would actually be correct
The example everybody uses
Here's the setup you see in almost every video. You have $10,000 in credit card debt. You bring home $3,000 a month. $1,000 goes to rent, $2,000 goes to expenses — food, groceries, gas, insurance. They say you have "zero cash flow," which I think just means you spend everything you make. And you have a $400 credit card payment.
The move is this: you keep the $1,000 in the bank for rent, because paying rent with a card usually costs you a fee. Then you take the $2,000 and make a payment on the credit card. Your balance drops from $10,000 to $8,000. During the month you still have to eat and buy gas, so you put those expenses on the card and the balance climbs back up.
If $1,600 of that $2,000 is actual expenses and $400 of it was the payment, you charge $1,600 back and end the month around $9,600. You're down $400 — which is exactly the payment amount. That makes sense.
Why you'd do it at all
The entire point is your average daily balance. Instead of carrying $10,000 all month, you carry something between $8,000 and $10,000. Say the average is $8,800. Your interest for the month might be $170 instead of $200. That's it. That's the benefit. It lowers interest because it lowers the average balance. It is not magic.
Myth 1: "Don't worry about the interest"
I saw someone say to just leave interest out of the calculation — don't add it in, keep cycling, and if it becomes a problem, go drive for Uber or get a side gig selling T-shirts. That drives me crazy. Interest is part of the math. If you leave it out, the payoff shows up faster than it really is and gives you a false impression of how powerful the method is. And if part of your "method" is go make more money, that's not velocity banking. That's the go-make-more-money method. Those are two different things.
Myth 2: The payment that "found" you $400
Same example. Zero cash flow, $400 required payment, $2,000 in expenses. Someone showed $10,000, minus the $2,000 payment, plus $2,000 charged back during the month — and ended at $9,600. That math is wrong. Take $10,000, subtract $2,000, add $2,000 back, and you're at $10,000.
Their reasoning was that because you sent the bank $2,000, you satisfied the $400 required payment, so you effectively found $400 you didn't have. Yes, the bank got its payment. No, that doesn't lower your balance. You turned around and charged $2,000 at a bunch of stores. The only way you'd land at $9,600 is if you charged $1,600 instead of $2,000 — meaning the $400 was already inside those expenses. That's the one case where their number works.
Key steps
- Write down your real income, your real expenses, and what you can and can't put on a card without a fee.
- Understand the only benefit: a lower average balance means less interest for the month.
- Always add the monthly interest into your projection. Every single month.
- Track what you charge back during the month. If you re-charge everything you paid, the balance doesn't move.
- Compare the result against a simple plan of just paying extra, using a credit card payoff calculator, and pick whichever actually pays off sooner.
FAQ
Does velocity banking actually work?
Yes, it works — it lowers your average balance, which lowers your interest for the month. But it's not as powerful as a lot of videos make it look, and the gains get wiped out fast if you leave interest out of your projection or re-charge everything you just paid down.
Why does leaving interest out matter so much?
Because interest is added every month, and it's a real cost. Leaving it out shows the debt paid off faster than reality. That's exactly why some people leave it out. If you want an honest picture, run it with interest included — the real math on paying off credit card debt walks through it.
What should I do instead if velocity banking seems confusing?
Nothing beats a plan you can actually follow. Pick a method, run the numbers, and go. The debt snowball calculator and the snowball vs. avalanche breakdown will get you a payoff date you can trust without any balance-shuffling.
How does velocity banking with a credit card work in the usual example?
You have $10,000 in card debt and bring home $3,000 a month. You keep $1,000 in the bank for rent and put $2,000 on the card, so the balance drops to $8,000. Then you charge food and gas back during the month. If $1,600 of that was real expenses, you end around $9,600, down $400, which is exactly the payment amount.
What is the only real benefit of the velocity banking strategy?
It lowers your average daily balance. Instead of carrying $10,000 all month, you carry something between $8,000 and $10,000. Say the average is $8,800. Your interest for the month might be $170 instead of $200. That's the benefit. It isn't magic, and going out to make more money is a different method, not velocity banking.
The step-by-step written version, with a worked example.